Notes from My Journey | A Longer View
There are things I thought I understood about building businesses. Not because I had read enough about them, but because I had spent years dealing with the consequences of decisions, some good, some not so good.
You begin to develop a certain confidence after a while. You recognise patterns. You become familiar with problems. You can often tell when something is unlikely to work, even before you have gone through all the numbers.
I suppose that is what experience is meant to do. But I have been wondering lately whether experience can also make us a little less willing to question ourselves.
It is an uncomfortable thought, particularly when you have spent a considerable part of your life building enterprises. You would like to believe that the years have given you better judgment. And perhaps they have. But better judgment does not necessarily mean that your assumptions are always better.
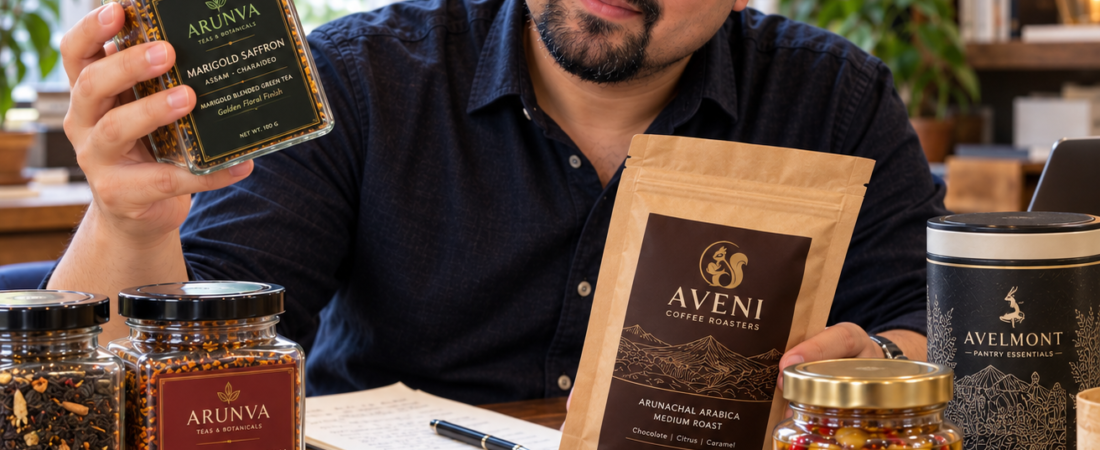
Sometimes they are simply older. I have been thinking about this while working on Avelmont Estate. We are developing three consumer businesses under the company: Arunva Teas, Aveni Coffee and Avelmont Essentials, our pantry portfolio.
When I first considered how these businesses could sit together, the advantages seemed reasonably clear. They could share infrastructure, administrative resources, certain distribution relationships and the financial and organisational capabilities of one enterprise.
There was nothing particularly unusual about that thinking. Businesses have been built around shared resources for generations. And I still believe the underlying idea makes sense. What I am less certain about is how much of the approach used to build one business can genuinely be carried into another. That uncertainty has been occupying more of my thoughts than I expected.
Tea is not just another business to me
I come from a plantation family. That matters to how I think about Arunva Teas, although I am not sure I have always appreciated how much it matters.
Tea was never simply an industry I discovered while exploring business opportunities. It was already part of the world I belonged to. The plantation economy, the relationship between land and production, the people involved and the commercial realities surrounding the industry were not entirely unfamiliar ideas.
There is a difference between approaching an industry as an outsider and approaching it with a sense of personal familiarity. The second can give you a certain understanding that is difficult to acquire from market reports.
It can also give you blind spots. I have caught myself thinking that I understand tea because I understand something of the world from which it comes. But understanding an industry and understanding the consumer who eventually buys your product are not the same thing.
A plantation produces tea. A consumer buys a particular tea for reasons that may have very little to do with the things a producer considers important.
Origin matters. Quality matters. Processing matters. But habit matters too. So does price, availability, familiarity and the small preferences people develop over years of consumption.
I find this interesting because, as a behavioural economist, I know that people do not make purchasing decisions through a neat calculation of objective product attributes.
We carry habits into the marketplace. We rely on familiar choices. We use price as a signal of quality, sometimes correctly and sometimes not. We develop preferences that we may struggle to explain.
Yet knowing these things intellectually does not prevent me from occasionally approaching a product with the assumptions of someone who knows its origins rather than someone who is encountering it on a shelf. That is something I have to keep reminding myself.
There is also an emotional attachment to tea that I do not want to pretend is absent. When something is connected to your family’s background, you naturally want to do it well. Perhaps you feel a greater responsibility towards it. Perhaps you are more particular about certain details. But emotional attachment can become a complication in business.
- It can make you more patient, which may be good.
- It can also make you less objective, which may not be.
I am still learning where that line lies.
Then there is coffee
Aveni Coffee presents a different kind of challenge. It does not carry the same personal history for me, and perhaps that allows me to approach it with a little more distance. But distance does not automatically produce better judgment. Coffee is a fascinating consumer category because the product is only part of what people purchase.
There is the daily habit of drinking coffee, certainly. But there is also the experience surrounding it. The way it is prepared, the interest in origins and roasting, the preferences people develop, and the social meaning that coffee has acquired in many markets.
Not every consumer approaches coffee this way. For many, convenience and familiarity remain more important than discovery. That difference itself makes the business interesting.
I cannot assume that someone who appreciates a premium tea will respond to a coffee brand in the same way. Nor can I assume that the language of quality and origin will carry identical meaning across the two categories.
And yet, from the company’s perspective, the temptation to treat them as closely related businesses is understandable. Both are beverages. Both involve sourcing, quality, packaging and consumer preferences. Both may reach certain overlapping retail channels. It would be convenient if much of the work done for one could simply be extended to the other. But convenience is not a business model.
I have to remind myself of that more often than I would like.
And the pantry business is another matter altogether
Avelmont Essentials brings us into a category where I suspect some of our assumptions will need even more examination. Pantry products occupy a different place in people’s lives.
A consumer may spend time considering a particular tea or exploring a new coffee. But many everyday pantry purchases are made with considerably less attention. People want something that works. They want consistency. They want to find it when they need it. They want a price that makes sense to them.
Brand matters, but the way it matters can be quite different. A pantry product may become part of someone’s regular household purchases without that person feeling any particular excitement about it. In fact, that may be one of the strongest signs that the product has found its place.
It has become familiar enough not to require much thought. There is an interesting behavioural dimension here.
We often talk about building consumer engagement as though greater attention is always desirable. But in many categories, the most valuable consumer relationship may be one in which the decision becomes almost automatic.
The consumer does not need to reconsider the product every time. Trust has become a habit. Of course, reaching that point requires consistency, availability and repeated satisfactory experiences. It cannot be achieved through a good brand story alone.
I find myself wondering whether we sometimes spend too much time thinking about how to persuade consumers to try something and too little time thinking about why they would continue buying it.
The first purchase is visible. The second, third and twentieth purchases are where a different kind of business begins to emerge. And that has implications for how we build Avelmont Essentials. It also means that the measures we use to understand its progress cannot simply be borrowed from Arunva or Aveni.
The comfort of a common structure
One of the reasons I wanted these businesses under one company was that I believed a shared structure would make the enterprise stronger. I still do. There is little sense in duplicating every administrative function or building separate organisational capabilities where one can support several businesses effectively.
Finance, governance, reporting, certain procurement activities and operational support can benefit from being brought together. A common enterprise can also allocate capital across opportunities in a more deliberate way. But I am beginning to see how easily the desire for efficiency can become an assumption that sameness is desirable.
It is an attractive assumption because it makes planning easier. You can imagine one distribution structure, one operational framework and a common approach to growth. The organisation appears simpler. The difficulty is that businesses do not become identical because they share an owner.
A distribution arrangement that works well for tea may be unsuitable for pantry products. A marketing approach that creates interest in coffee may have little effect on the purchasing decisions surrounding everyday household essentials. Even the meaning of a successful month may differ considerably between the three.
And this is where I have started looking more carefully at the numbers.
The numbers do not always tell the same story
There is something reassuring about financial reports. They bring different activities into a common language. Revenue, costs, margins, investment and returns can be compared. They allow us to step away from the enthusiasm surrounding a product and examine what is actually happening. But numbers can also conceal differences when we combine them too quickly. Suppose the three brands are growing at different rates.
One may generate attractive gross margins but require considerable investment in consumer acquisition. Another may operate on tighter margins but benefit from frequent repeat purchases. A third may need more time to develop distribution before its economics begin to improve.
If I look only at the portfolio’s overall revenue growth, I may feel reasonably satisfied. But what exactly is growing? Which brand is creating value? Which one is consuming resources? Which one is improving its position, and which is simply benefiting from the performance of the others?
A consolidated number cannot answer all of those questions.
I have been thinking about this because it is easy for a founder to become attached to the overall story of an enterprise. We are building three brands. We are expanding the portfolio. We are creating shared capabilities. All of that may be true. But it does not tell me whether each business has a credible economic future.
My present approach is to examine the economics of each brand separately while considering capital allocation and shared capabilities at the portfolio level. That distinction is becoming increasingly important to me.
Tea, coffee and pantry products do not necessarily have comparable gross margins, purchase frequencies, working-capital requirements or investment timelines. Applying one return threshold to all three could produce conclusions that are mathematically consistent but commercially misleading.
At the same time, treating each brand as though it exists entirely on its own would overlook part of the reason for building them together. Shared infrastructure can create value. Distribution relationships may benefit more than one business. Some investments may support the portfolio without being attributable neatly to a single brand.
I do not want to ignore those advantages simply because they are difficult to allocate precisely. But neither do I want them to become a convenient explanation for weak performance. That is the uncomfortable part.
There is a difference between allowing a young business time to develop and allowing it to depend indefinitely on the success of another.
- The first may be a sensible investment decision.
- The second can become a habit that is increasingly difficult to question.
And I know enough about human behaviour to recognise how easily we can justify continuing something simply because we have already committed ourselves to it.
We become attached to our investments. Not only financially, but emotionally. We remember why we began. We remember the work that has gone into the idea. We remember the possibilities we imagined. And when the numbers begin asking difficult questions, it is tempting to answer with the original ambition.
But ambition cannot substitute for economic viability.
I do not believe every young brand must deliver the same returns or reach profitability on the same timetable. Some businesses require longer periods of investment. Others may begin generating cash earlier.
What matters is whether each has a credible path towards sustainable returns, and whether the company is making a conscious decision about the resources it continues to commit.
We are still developing that balance at Avelmont Estate. I would be pretending if I said we had resolved it.
The difficulty of questioning your own decisions
There is a particular discomfort in reconsidering a decision you made yourself. When someone else proposes an idea, it is relatively easy to examine its weaknesses.
When the idea is yours, the process becomes more complicated. You know why you made the decision. You remember the alternatives. You can explain the reasoning behind it. And sometimes that explanation becomes a defence. I have noticed this tendency in myself.
Not necessarily in dramatic ways. More often in ordinary business decisions, where an earlier assumption continues to influence the next discussion because nobody has found a sufficiently strong reason to reopen it.
The problem is that circumstances do not need our permission to change. Markets evolve. Costs change. Consumer preferences shift. Opportunities that looked attractive six months earlier may no longer justify the same commitment. There is no particular virtue in holding on to a decision simply because it was reasonable when it was made.
Yet changing course can feel like admitting that the earlier judgment was wrong. I think this is where behavioural economics becomes personal. It is easy to discuss sunk costs, loss aversion and confirmation bias when examining other people’s decisions.
It is less comfortable to recognise them in your own. I can understand why an investor continues supporting a struggling venture. I can explain why people tend to seek information that confirms what they already believe. I know why giving up an anticipated gain can feel more painful than never having imagined it.
But understanding a bias does not make me immune to it. Sometimes it simply makes me more aware of the argument taking place in my own mind. And perhaps that awareness is useful, even when it does not immediately settle the decision.
I also have to question my own involvement
There is another matter I have been thinking about, and this one concerns the way I work. When you are developing a business, being involved in everything can feel entirely reasonable.
You want to understand the product. You want to examine the costs. You want to know what the suppliers are offering, what the market may accept and whether the decisions being made are consistent with the direction you have in mind.
There is a sense of responsibility attached to that involvement. And, I must admit, a certain comfort. When I am closely involved, I know what is happening.
But what happens when the business grows?
- If Arunva, Aveni and Avelmont all require my attention for every meaningful decision, have I really created a stronger organisation?
- Or have I simply created more work for myself?
I do not particularly enjoy that question. Partly because I know the answer is not always flattering. Founders often speak about delegation as though it is a straightforward management exercise. Identify the right people, assign responsibilities and allow them to execute. But delegation is also an emotional decision.
It means accepting that someone else may approach a problem differently. It means allowing decisions to be made without possessing every detail yourself. It means accepting that an organisation cannot develop independent judgment if the founder insists on supplying all of it.
And there is a contradiction here. I want to build enterprises that can eventually function as institutions. Yet the instinct to remain involved in every important decision can work against precisely that ambition. I can justify my involvement by pointing to the early stage of the businesses. And sometimes that justification is entirely valid.
But I also need to recognise when involvement stops being necessary and becomes familiar. Those are not the same thing.
Being busy is not the same as building
I have begun to look at busyness with a little more suspicion. There is always something happening when you are developing several businesses. A product needs attention. A supplier has a question. A pricing decision must be reviewed. A packaging detail needs approval. A distribution possibility appears. Another problem requires an immediate response.
It is easy to finish a day feeling that a great deal has been accomplished. Sometimes it has. But I have been asking myself whether all that activity is making the enterprise more capable.
- Are we creating processes that reduce unnecessary dependence?
- Are people becoming better at making decisions?
- Are responsibilities becoming clearer?
- Are we learning which activities should be shared and which require specialised attention?
- Or are we simply becoming more efficient at keeping ourselves occupied?
That last possibility bothers me. I do not want to confuse the volume of work with the quality of progress. An enterprise can become increasingly complicated without becoming more valuable.
It can employ more people, introduce more products and enter more markets while remaining dependent on the same small number of individuals to make everything function.
- From the outside, that may look like growth.
- From the inside, it can feel very different.
I have come to believe that one of the quieter measures of progress is whether an organisation can handle more responsibility without requiring a proportional increase in the founder’s personal involvement. That is easier to write than to achieve. I am aware of that.
The things we do not measure
As an economist, I naturally look for ways to measure progress. But I have also become increasingly conscious of what our measurements leave out. Revenue tells us something important, but not everything.
Gross margin tells us something about product economics, but not necessarily the full cost of building demand. Repeat purchases reveal something about consumer behaviour, but their significance depends on the category and the circumstances.
A brand may appear successful because it is receiving support from capabilities developed elsewhere in the portfolio. Another may appear less attractive because it is bearing costs that will eventually benefit the wider company.
These are not reasons to abandon measurement. They are reasons to be careful about what we think the measurements mean. I also wonder about the things that are harder to put into a spreadsheet.
- The quality of decisions being made.
- The ability of a team to recognise a problem before it becomes expensive.
- The willingness to challenge an assumption.
- The discipline to stop pursuing an opportunity that no longer makes sense.
- The confidence to make a decision without seeking approval for every detail.
These capabilities may not produce immediate revenue. But their absence can become costly. Perhaps that is why I am increasingly interested in the difference between expanding a business and strengthening it.
Expansion is visible. Strength is often discovered only when something does not go according to plan.
I do not want three versions of the same brand
When I think about the future of Avelmont Estate, I do not imagine Arunva, Aveni and Avelmont Essentials becoming variations of one commercial formula.
I want them to have a common foundation without losing their individual character.
- Arunva should be able to build around tea, its origins, its quality and the preferences of the people who drink it.
- Aveni should develop its own understanding of coffee consumers and the opportunities within that category.
- Avelmont Essentials should establish its place through the reliability, value and consistency expected of everyday pantry products.
The company behind them should provide the discipline, resources and capabilities that make those ambitions possible. But it should not force them to behave as though their markets are identical. That is the distinction I am trying to work towards. And I suspect it will require more patience than I originally imagined.
Not the passive kind of patience where we wait and hope things improve. The more difficult kind, where we allow a business time to develop while continuing to ask whether our assumptions remain valid. There is a fine line between patience and avoidance.
I would like to think I can always recognise it. I know I cannot. That is another reason to build systems and people capable of questioning decisions independently of me.
Perhaps this is what experience is really for
I have been thinking about what I would tell my younger self about building businesses. I am not sure I would give him a long list of lessons. I might simply tell him to remain a little less certain.
Not less ambitious. Not less willing to take risks. Just less certain that an approach which worked before must work again. There is something liberating about accepting that experience does not give you permanent answers. It gives you references. It gives you judgment. It helps you recognise familiar difficulties.
But it cannot remove the need to understand what is different about the next undertaking. And perhaps the greatest danger is not making a wrong decision. It is becoming so invested in being right that we stop noticing when a decision needs to change.
I am still working through these questions at Avelmont Estate. There are things I feel confident about. There are others I am less sure of. Some of the decisions we are making now will probably look different to me a year from today. I hope I will have the willingness to reconsider them when necessary.
I also hope I will remember that the purpose of building several brands under one company is not simply to make the portfolio larger. It is to create an enterprise capable of supporting different businesses, allocating resources responsibly and developing the judgment to know when something should be shared and when it should remain distinct.
That may sound like a modest ambition compared with the excitement of launching new products and entering new markets. But I am beginning to think it is the more difficult one. And possibly the more important.
Before this becomes another lesson
There is something about writing these thoughts down while I am still in the middle of the experience. Usually, we tell stories about business after the difficult parts have passed. We explain why a decision worked. We identify the mistake. We describe what we learnt.
The story becomes orderly. But life inside an enterprise rarely feels that orderly. Decisions are made with incomplete information. Some assumptions are tested almost immediately. Others remain unchallenged for much longer than they should.
- You make compromises.
- You change your mind.
- You occasionally return to an idea you had previously dismissed.
And sometimes you discover that the problem was not the market, the product or the people. It was the way you had been thinking about them.
- I do not know yet how every part of Avelmont Estate will develop.
- I do know that I am approaching these three brands with a slightly different understanding from the one I began with.
- The shared company still makes sense to me.
- The opportunities still interest me.
- The ambition remains.
But I am becoming more careful about assuming that what is common between the businesses is necessarily more important than what makes them different. And I am becoming more conscious of my own tendency to carry familiar solutions into unfamiliar situations.
Perhaps I will read this note a few years from now and disagree with parts of it. That would not trouble me. I would be more concerned if I had learnt nothing that made me reconsider what I believed today. For now, I want to remember one thing.
Building something new is not simply an opportunity to apply what experience has taught me. It is also an opportunity to discover where that experience may have made me too certain. And I would rather recognise those limits while I am still building than discover them only after the cost of ignoring them has become difficult to bear.
That, at least, is where my thoughts are today.