Some of the most consequential economic decisions never appear in the data. They are the factories postponed, people not yet hired, markets not entered and investments that almost made sense.
Economics has a habit of becoming more abstract as the numbers get bigger. We talk about interest rates, inflation, investment, liquidity and growth at the level of an economy. We examine what central banks are doing, whether credit is expanding or contracting, and whether businesses are investing enough.
All of this is necessary. But running an enterprise makes you encounter these same forces from the opposite direction. They arrive as decisions.
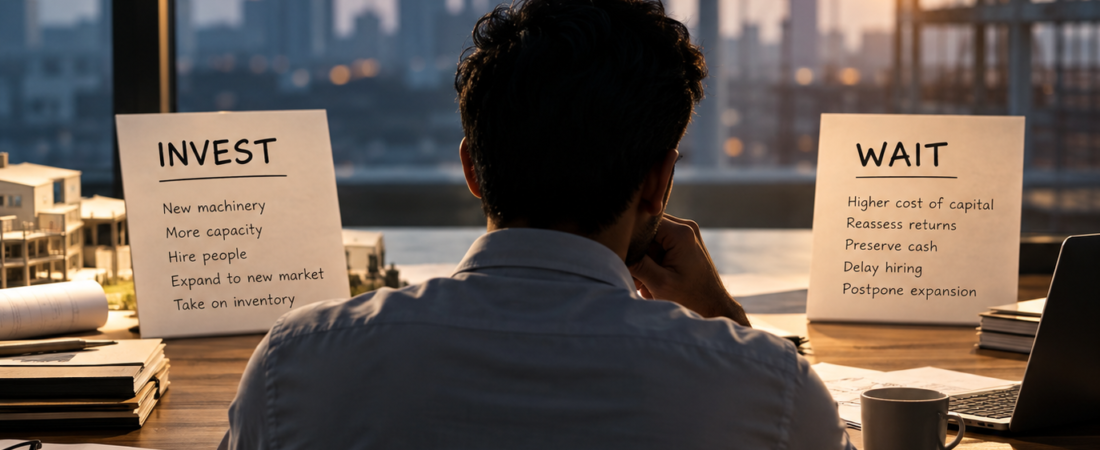
A machine that seemed worth buying six months ago is postponed. Inventory is kept a little tighter. A new location goes through another round of calculations. Recruitment for an expansion slows down. A project that everyone still believes in is quietly moved from “now” to “later.” Sometimes nothing more dramatic happens than deciding to keep the cash. This is one of the reasons I find the cost of capital particularly interesting. It sounds like a financial concept, but its consequences are deeply operational.
When the project hasn’t changed
Consider a deliberately simplified example. Suppose a business is evaluating an expansion that it reasonably expects could generate a return of around 12 per cent. If the effective cost of financing that investment is 8 per cent, there is a meaningful margin between the expected return and the cost of the capital being put at risk. It does not make the investment safe—business rarely offers that luxury—but it gives management room to consider proceeding.
Now move the effective cost of capital towards 11 per cent.
Something interesting happens. The factory has not changed. The machine has not become less productive. The customers have not disappeared. The expected sales might be exactly where they were before. Yet the decision feels completely different. What disappeared was not the opportunity. It was the margin for error.
An entrepreneur now has to ask whether that remaining return adequately compensates for all the things that could go wrong: slower sales, higher input costs, implementation delays, an unexpected regulatory change, a customer who pays late, or simply an economic environment that becomes less favourable.
At some point, the rational answer becomes:
Not yet.
How macroeconomics reaches the shop floor
This is where macroeconomics becomes remarkably ordinary. An interest-rate decision made at the level of monetary policy eventually arrives at a desk somewhere as a question about whether to buy another machine. It reaches a retailer deciding how much inventory to carry. It reaches a manufacturer considering another production line. It reaches an entrepreneur deciding whether to enter a new city.
And it reaches a company deciding whether the expansion it had planned justifies hiring ten more people today or six months from now. No single one of these decisions will attract much attention. But multiply them across thousands of businesses and they begin to explain how changes in financial conditions eventually influence investment, employment and economic growth.
There is also a timing problem. Businesses do not all react at once. Existing loans may remain at earlier rates. Projects already underway may continue. Companies with strong cash reserves may barely notice the change initially, while heavily financed businesses feel it almost immediately.
The transmission of monetary conditions through the real economy is therefore neither instantaneous nor uniform. It moves through individual balance sheets and individual judgements.
The cost of capital is more than an interest rate
There is another distinction worth making. The interest rate is not necessarily the same thing as the effective cost of capital faced by an enterprise. Two businesses operating under the same central-bank policy can face very different financing realities. One may have a long credit history, substantial assets, predictable cash flows and several lenders competing for its business. Another may be younger, smaller, operating in a less familiar sector or located somewhere lenders perceive as more difficult.
Their underlying economic opportunities could be equally attractive. Their access to capital may not be. This is why discussions about productive investment cannot stop at whether policy rates should be higher or lower. The cost attached to capital also contains an assessment of risk.
And some of that risk comes from the wider environment in which the business operates.
- How predictable is regulation?
- How long does it take to enforce a contract?
- How easily can collateral be realised?
- How deep are the country’s credit markets?
Is long-term financing available, or are businesses attempting to finance long-duration investments with short-duration money? How confident are investors that the rules under which they make an investment today will remain reasonably stable tomorrow? Each of these questions eventually finds its way into the return somebody expects before putting capital at risk. Improving those conditions can therefore matter just as much as arguing about the headline interest rate.
Cheap money has a cost too
It would be tempting to take the argument this far and conclude that cheaper capital is always preferable.
It isn’t.
If money remains unusually cheap for too long, investments that should never have been made can begin to look viable. Companies can take on more leverage than their underlying businesses justify. Asset prices can move away from fundamentals. Capital can remain trapped in businesses that survive because financing is inexpensive rather than because they are productive.
The objective, therefore, cannot simply be the cheapest possible money. It should be something more difficult: reasonably priced capital reaching genuinely productive investment. That requires a functioning financial system capable of distinguishing risk rather than merely avoiding it. It also requires an institutional environment that reduces unnecessary risk. A business should pay for the commercial risk inherent in its investment. It should not have to price an excessive premium for uncertainty that could have been reduced through better institutions, clearer rules or more efficient systems. That distinction matters.
The economy we cannot see
Economic statistics are necessarily built around things that happened. We can count a factory once it is constructed.
- We can record investment once money is spent.
- We can measure employment once somebody is hired.
- We can observe production once another unit leaves the factory.
What is much harder to measure is everything that nearly happened. The factory whose numbers worked at one financing cost but not another. The additional production line that management postponed. The new market that remained on the drawing board. The ten people who would have been hired if the expansion had begun. None of these appears as a failed investment because, technically, no investment failed. It simply never happened. This invisible economy matters because expectations about tomorrow influence decisions made today.
An entrepreneur who believes financing conditions will improve may wait. One who expects uncertainty to persist may abandon the project entirely. Another may reduce its scale. Someone else may decide that the same capital is better deployed somewhere different. These are rational responses to the information available at the time. But collectively they shape the future productive capacity of an economy. This is why I increasingly think that one of the most useful ways to understand economic conditions is not only to ask businesses what they are doing.
We should also ask:
What would you have done under slightly different conditions?
The answer may tell us something that investment statistics cannot. Because sometimes the most consequential economic decision is not a factory that closed, a business that failed or an investment that lost money.
It is the entrepreneur who looked at an otherwise promising opportunity, ran the numbers one more time, and decided:
Not yet.